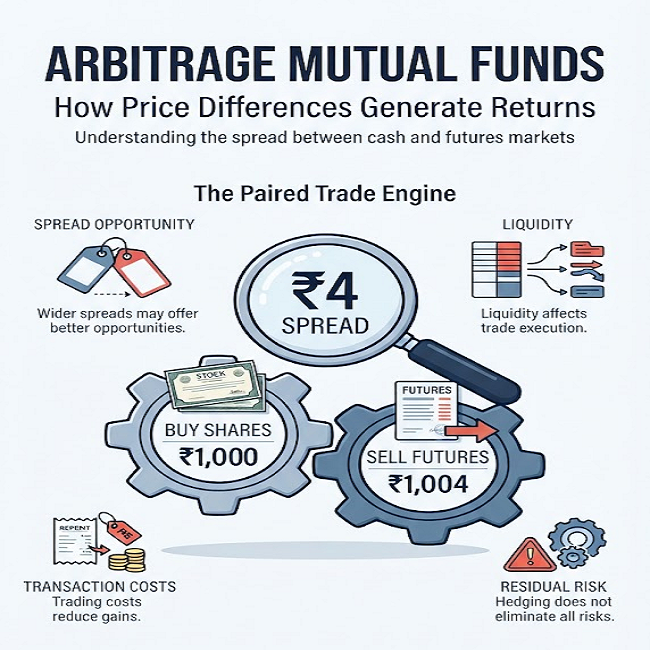
The stock may be worth ₹1,000 in the cash market whereas the one-month future of the same contract could be worth ₹1,004 on the very same day. This difference does not occur due to any pricing error, differences like this are what arbitrage mutual funds try to collect. It is primarily an indicator of the cost involved in holding the contract till the maturity date of the contract.
What are Arbitrage Mutual Funds?
Classification under SEBI’s scheme classification indicates that arbitrage funds are open-ended schemes that invest in arbitrage transactions while keeping at least 65% of their net assets in equities and equity related securities. Essentially, the mutual fund scheme buys the stocks in the cash market and sells the future contracts of those stocks in similar quantity. The remaining amount of money is typically parked in debt and money market instruments.
Arbitrage hedges against market movement risks. It does not eliminate risks. They are the market-linked mutual fund schemes and not savings instruments and the NAV could decline.
How Do Arbitrage Funds Generate Returns?
Assume a situation where the fund purchases 1,000 shares worth ₹1,000 and sells one-month futures contracts on these at ₹1,004. The spread of ₹4 is booked at inception.
The futures contract price moves towards cash price at expiry. If the stock ends up at ₹1,050, there will be a profit of ₹50 on shares and loss of ₹46 on futures. If it falls to ₹950, there will be a loss of ₹50 on shares but gain of ₹54 on futures. In either scenario, the net profit comes to ₹4.
After deducting the cost, which may be assumed at ₹1.20 per share including brokerage, securities transaction tax, etc., there will be a net gain of ₹2.80 or 0.28% on ₹1,000 for the month. The above example is purely for illustration purpose only and actual figures keep changing every day.
What Influences Arbitrage Fund Returns?
This is where the spread comes into play. The wider the spread between futures and the cash market, the better for the strategy. The narrower the spread or even an inverse one, the worse. Spreads usually increase during strong purchasing in futures and therefore such periods can be favorable although it is not certain.
Then there are the costs. Every entry and exit as well as each month’s roll brings its cost, and in case of a highly active fund they can be substantial. And again, liquidity will matter. Big funds require large amounts to be traded while still not influencing the market in opposite direction, and thus limiting the number of stocks that are feasible to use. And finally, there are the fund’s expenses that are deducted from all gains. Future gains cannot be assessed by past gains as they depend on future conditions.
Arbitrage Funds vs Liquid and Debt Funds
Liquid funds invest in debt and money market instruments with short maturities. Liquid mutual funds returns are driven mainly by interest accrual, which means they follow short-term rates, and the funds carry limited credit and interest-rate risk, depending on the portfolio.
Debt funds are not one category. Within fixed income mutual funds, schemes range from overnight and ultra-short to long-duration and credit-risk funds. The debt funds return an investor sees depend on the maturity profile, the credit quality of holdings and the direction of interest rates. A gilt fund and a credit-risk fund can behave very differently.
Arbitrage funds are immune to interest rate risks due to hedged equity positions, but they suffer from execution, liquidity, and derivatives risks. The returns on arbitrage funds are somewhat dependent on short-term interest rates, which can be seen in part from the fact that premium of futures includes carry cost, although it is not very significant.
Risks and Investor Considerations
- Spreads can be small or negative for periods of time causing low returns.
- The costs that come from execution slippages and transactions will take away any profits.
- Hedges can be hard to get rid of during times when markets are not stable which leads to lower Net Asset Value of the fund.
- Profitability changes from one month to another, Sometimes even causes negative returns.
Look at the details on the scheme’s investment policy, expense ratio and exit load from the documents of the scheme before making an investment.
Regarding tax at the time of writing this article various sources say that arbitrage funds that meet the rules of being equity-oriented will be considered as equity funds. Gains from units held for than 12 months are taxed at 20%. The long-term gains from these units will be taxed at 12.5% on gains over ₹1.25 lakh each year, in equity.
Conclusion
Arbitrage funds can fit well in a portfolio for money that you don’t need right away and can leave invested for a short to medium time. These funds work best for investors who know how the returns are generated and are okay with profits that come irregularly and aren’t guaranteed. Before deciding whether to go with arbitrage funds or liquid funds or debt funds take a look, at your investment timeline how quickly you might need cash, your tax situation and how much risk you are willing to take.